Pension portfolios under long-bond stress
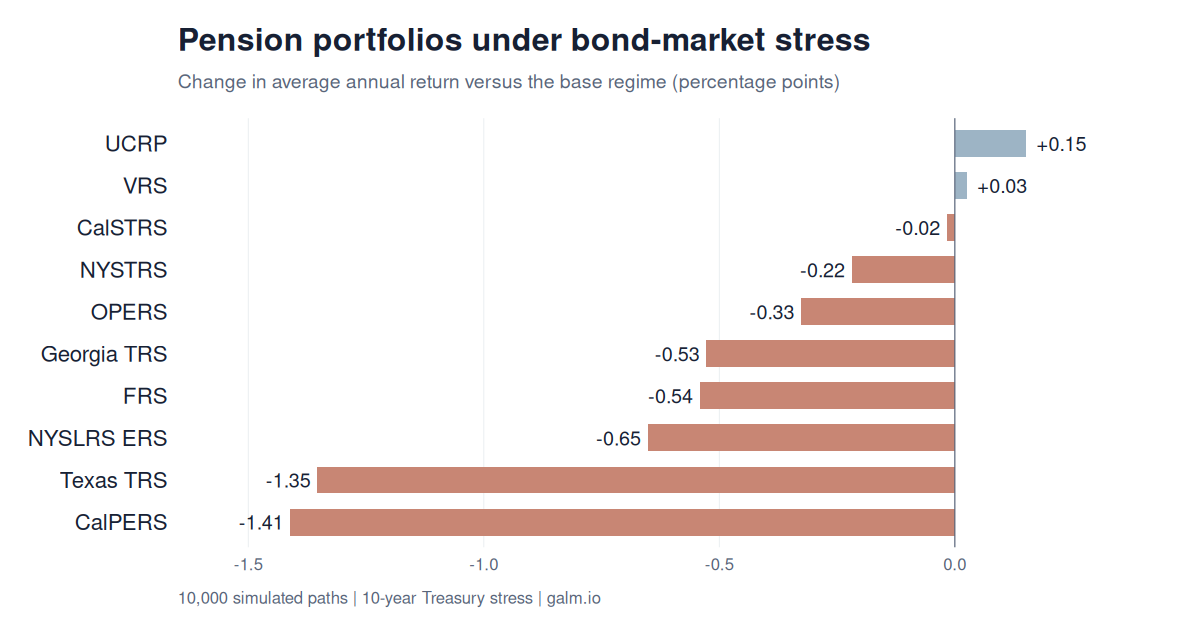
Across the ten largest US public pension portfolios, simulated average annual returns remain positive under bond-market stress but fall 49 basis points below the base regime. CalPERS and Texas TRS show the largest declines, while allocation and bond tenor together help explain differences in resilience.
Read the analysis